
How to Budget a Home Renovation With Phased Payments
A phased payment schedule ties each draw to verified milestones, protecting your cash flow and keeping contractor leverage. Call (833)-365-8755 to plan your budget.
By Irene Walsh
Learn more about Home Remodeling for guides, costs, and what to expect.
Compare Home Remodeling Pros Near You

Enter your ZIP code to compare top-rated local professionals and request free quotes.
A home renovation is one of the largest financial commitments a homeowner will make, and the way you release money during the project can matter as much as the total budget itself. Pay too much upfront and you lose leverage; pay too slowly and you may stall your crew. The solution is a phased payment schedule: a written plan that ties each disbursement to a completed, verifiable milestone. This approach protects your cash flow, keeps the contractor accountable, and turns a stressful financial outlay into a controlled, predictable sequence. Whether you are remodeling a kitchen, replacing a roof, or finishing a basement, understanding how to budget a home renovation with a phased payment schedule is the single most effective way to avoid surprise bills and unfinished work.
Why Phased Payments Beat a Large Upfront Deposit
Many homeowners instinctively hand over a substantial deposit to "secure" a contractor and lock in a start date. While a small mobilization deposit is normal, paying 30 to 50 percent before any work begins is a red flag. Large upfront payments remove your leverage: if the contractor walks away, runs into financial trouble, or simply deprioritizes your job, your money is already gone. Consumer protection agencies across the country consistently warn against contractors who demand large cash deposits or full payment before work starts.
A phased schedule flips the risk equation. You pay for value received, not promises. Each payment is released only after a defined portion of the work is complete and inspected. This structure also keeps the contractor financially motivated to finish each phase, because the next payment depends on it. For homeowners managing a fixed budget, phased payments spread the cash outlay over weeks or months, making it easier to align spending with savings, financing draws, or a home equity line of credit. If you are still deciding how to fund the project overall, our guide on how to finance home renovation explains the main options before you commit to a payment structure.
Typical Deposit and Draw Schedules by Project Type
There is no universal payment schedule, but industry norms exist for common projects. A reasonable deposit is usually 10 to 20 percent of the contract price, sometimes capped at a fixed dollar amount. The remaining balance is divided into draws, typically three to five payments tied to milestones. The table below outlines common structures, though your specific contract should always reflect your project scope and local regulations.
- Kitchen or bathroom remodel: 15 percent deposit, then draws at demolition completion, rough-in inspections, cabinet or tile installation, and final punch list.
- Roof replacement: 10 to 15 percent deposit, a material delivery draw, a mid-project draw after tear-off and decking, and final payment after inspection and cleanup.
- Whole-home renovation: 10 percent deposit, then monthly or milestone-based draws (foundation, framing, mechanicals, finishes), with a 5 to 10 percent retainage held until final walkthrough.
- Flooring or painting: 10 percent deposit, a material delivery payment, and the balance upon completion and your approval.
Notice that every structure holds back a meaningful final payment, often called retainage, until the job is fully complete. That final 5 to 10 percent is your strongest tool for ensuring punch-list items are finished and cleanup is done. Without it, small incomplete items can drag on for weeks.
The Risk of Paying Ahead of Completed Milestones
Paying ahead of completed work is the most common budgeting mistake homeowners make. It happens when a contractor asks for the next draw early, citing material costs, payroll, or a scheduling crunch. Sometimes the request is legitimate, but often it signals cash-flow problems at the contracting company. Once you pay for work that has not been done, you have no guarantee it will ever be done.
A disciplined rule is simple: never release a payment until the milestone is complete and you have inspected it. If a contractor needs help with material costs, negotiate a separate materials draw with receipts and a lien waiver, rather than advancing the labor portion. Keep a written log of every payment, the date, the amount, and the milestone it covered. This log becomes your evidence if a dispute arises, and it makes the final accounting much easier.
Tying Payments to Inspections and Punch-List Sign-Offs
The most protective payment schedules attach each draw to an objective event, not a subjective claim of progress. Whenever possible, link payments to third-party inspections or written sign-offs. For projects involving structural, electrical, or plumbing work, municipal inspections provide independent verification that the work meets code. A draw released after a passed inspection is far safer than one released after a verbal "we are almost done."
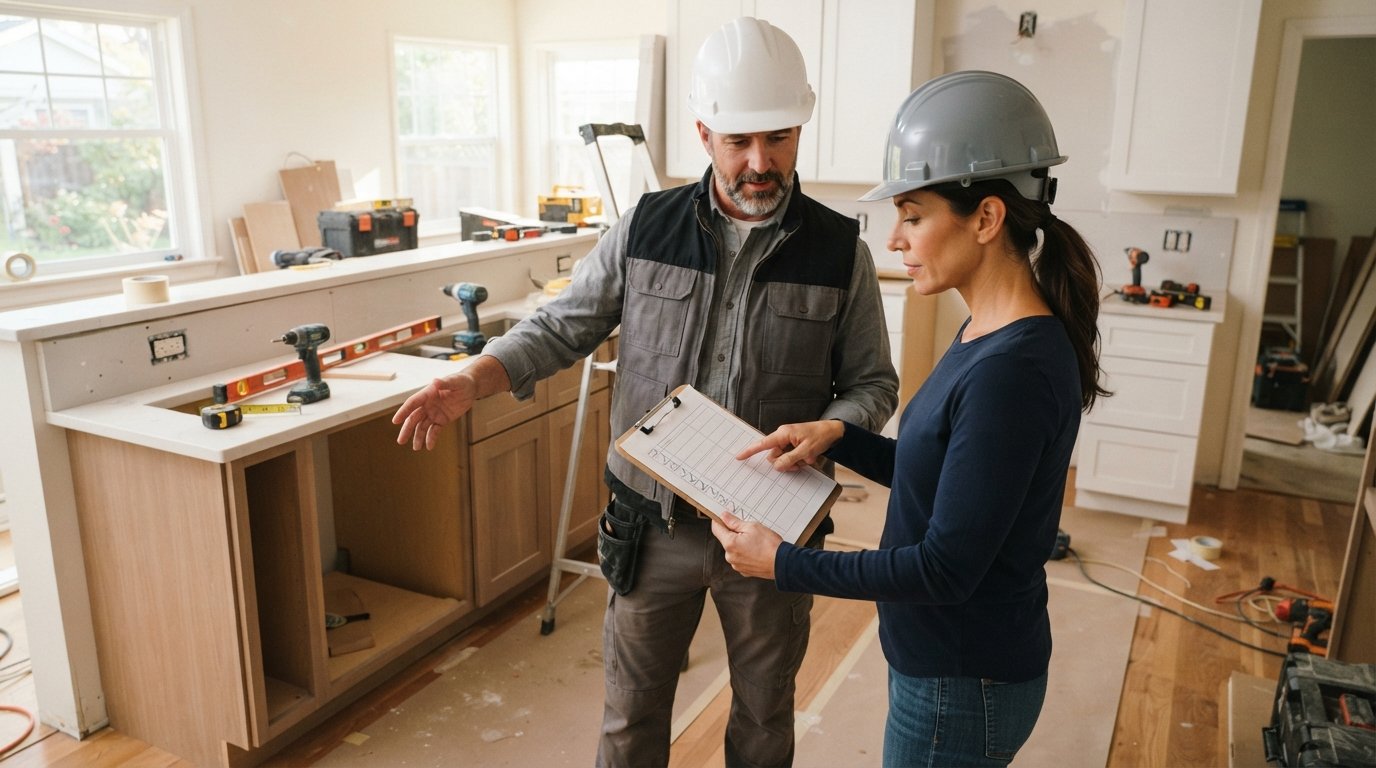
For finish work that does not require permits, use a written punch list. Walk the site with the contractor, list every incomplete or defective item, and agree in writing that the payment will be released when the list is cleared. Photograph each milestone before paying. This habit takes minutes but prevents disputes worth thousands. It also reinforces a professional relationship: clear expectations on both sides reduce friction and keep the project moving.
Lien Waivers and Final Payment Timing
A lien waiver is a document in which a contractor or subcontractor confirms they have been paid for work performed and gives up the right to file a mechanic's lien against your property. Liens are a serious risk in renovation projects because unpaid subcontractors or suppliers can place a lien on your home even if you paid the general contractor in full. To protect yourself, request a conditional lien waiver with each progress payment and an unconditional final lien waiver before releasing the last payment.
Final payment should be held until three conditions are met: the punch list is complete, all final inspections have passed, and you have received unconditional lien waivers from the general contractor and major subcontractors. Some homeowners also hold a small retainage for 30 days after completion to cover any latent defects. Whatever terms you choose, put them in the contract before work begins, not after a dispute emerges. For homeowners who want to compare vetted contractors with transparent pricing, a resource like PlanRemodel can help you find qualified professionals in your area before you negotiate payment terms.
Contract Language to Negotiate Before Work Starts
The payment schedule should be written into the contract with enough detail that there is no ambiguity. Before signing, negotiate the following terms and confirm each one appears in writing. A well-drafted payment clause protects both parties and sets the tone for the entire project.
- Deposit amount and cap: Specify a percentage or fixed dollar cap, and confirm it covers mobilization and materials only.
- Milestone definitions: List each draw amount and the exact work that must be complete before it is released.
- Inspection and sign-off process: State who inspects, how approval is documented, and the timeline for releasing payment after approval.
- Retainage and final payment: Define the percentage held back and the conditions (punch list, inspections, lien waivers) required for final release.
- Change order procedure: Require written, signed change orders with pricing before any additional work begins, so the payment schedule can be updated fairly.
If a contractor resists putting a detailed schedule in writing or insists on a large upfront payment, treat that as a warning sign. Reputable professionals expect to document milestones and are comfortable with inspection-based draws. A clear schedule also protects the contractor by proving when payments are due, which reduces awkward conversations mid-project.
Building Your Renovation Budget Around the Schedule
Once the payment schedule is set, map it against your own cash flow. Add up all draws and note the dates or milestones when each will come due. Then confirm you will have funds available at each point, whether from savings, a construction loan, or a financing draw. Build a contingency of 10 to 20 percent on top of the contract price, because renovations routinely uncover hidden issues such as water damage, outdated wiring, or code violations. That contingency should be held separately and released only for approved change orders.
Track spending in a simple spreadsheet with columns for date, milestone, amount invoiced, amount paid, and remaining balance. Review it weekly with the contractor so both sides see the same numbers. This discipline is the practical answer to how to budget a home renovation with a phased payment schedule: a written plan, verified milestones, held-back retainage, and a contingency reserve. Homeowners who follow this structure consistently report fewer surprises, stronger contractor accountability, and a calmer renovation experience from first draw to final walkthrough.