
Home Renovation Insurance Coverage for Projects: What You Need
Home renovation insurance coverage for projects protects your investment when the unexpected happens. Verify contractor policies and fill coverage gaps before work begins.
By Margaret Lowe
Learn more about Home Remodeling for guides, costs, and what to expect.
Compare Home Remodeling Pros Near You

Enter your ZIP code to compare top-rated local professionals and request free quotes.
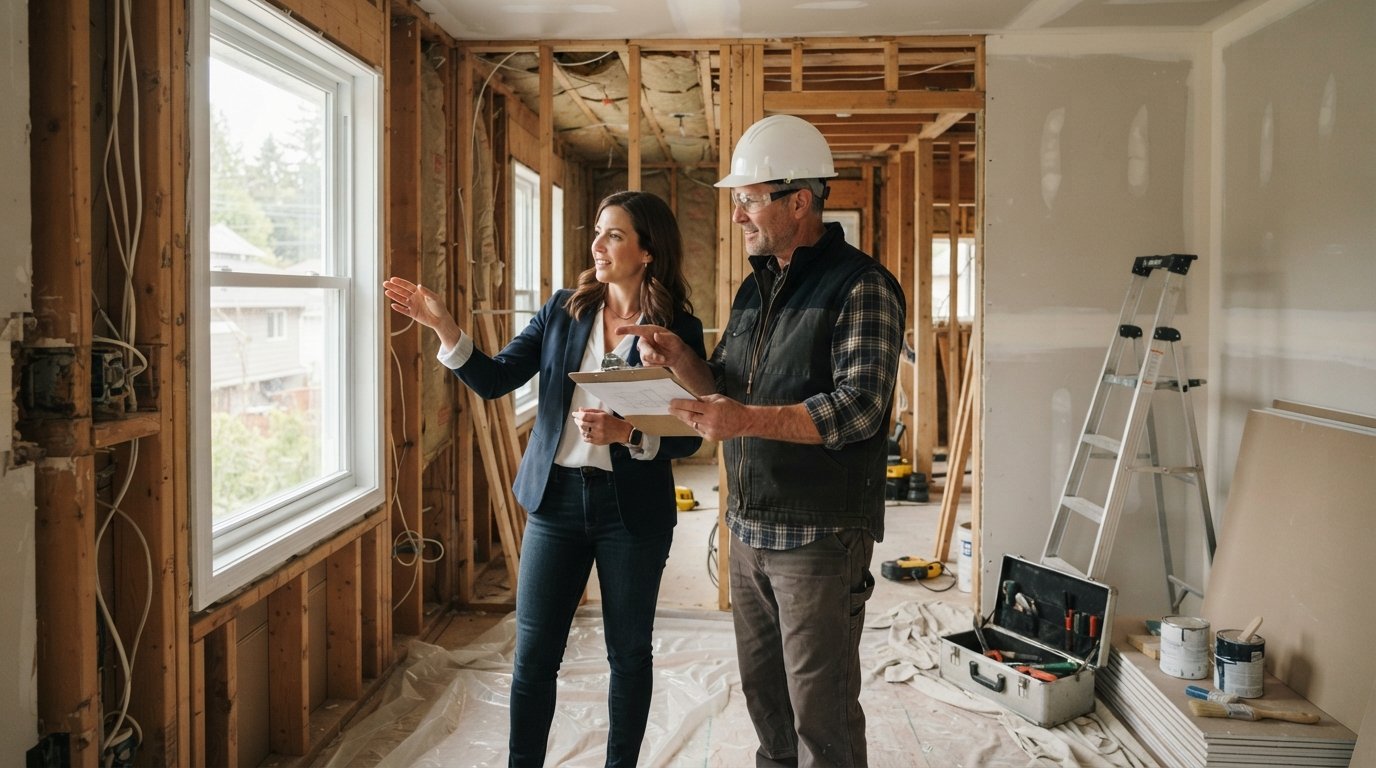
Your contractor just backed a truck through your garage door, a pipe burst behind the new drywall, or a delivery driver tripped on your temporary walkway. Any of these events can turn a dream remodel into a financial nightmare. The good news is that home renovation insurance coverage for projects exists to protect you in exactly these moments. The bad news is that most homeowners assume their standard policy handles everything, and that assumption can cost them thousands. Understanding how insurance works during a remodel is not optional homework. It is the difference between a protected investment and a devastating surprise.
Why Your Standard Homeowners Policy May Fall Short
Most homeowners policies are built around a simple idea: they insure the home as it stands today. The moment you start tearing out walls, adding square footage, or storing $15,000 worth of tile in the garage, the risk profile of your property changes. Insurers know this, which is why many policies contain clauses that reduce or void coverage during active construction. A vacant or under-construction home is viewed differently than a fully occupied, stable residence.
There is also the matter of who is legally responsible when something goes wrong. If a subcontractor injures themselves on your property, or if faulty electrical work causes a fire, the liability question becomes far more complicated than a standard policy anticipates. Your neighbor's tree falling on your roof is one thing. Your electrician's mistake burning down the addition is another story entirely.
Even the timeline of your project matters. According to our guide on how long a home renovation takes, even modest projects stretch across weeks or months, and every additional day is another day your property sits in a heightened risk state. The longer the exposure, the more likely an insurer will scrutinize a claim.
The Main Types of Coverage You Should Evaluate
Home renovation insurance coverage for projects is not a single product. It is a bundle of protections that may come from your existing policy, your contractor's policy, or a dedicated renovation policy you purchase yourself. Knowing which layer covers which risk prevents the finger-pointing that follows a major loss.
Here is a breakdown of the core coverage types every homeowner should confirm before demolition day:
- Dwelling coverage during construction: Extends your existing structure protection to the new work, materials on site, and partially completed additions.
- General liability (contractor's policy): Covers third-party injuries and property damage caused by the contractor's operations, but only if the contractor is properly insured.
- Workers compensation: Protects injured crew members and shields you from lawsuits if an uninsured worker gets hurt on your property.
- Builder's risk insurance: A specialized policy for major renovations that covers the project itself from start to finish, including materials, fixtures, and the structure.
- Valuable items or rider coverage: Protects high-end fixtures, appliances, and custom materials stored on site before installation.
The right combination depends on the scope of your project, the value of your home, and the insurance your contractor already carries. A minor bathroom refresh may only require a certificate of insurance from your contractor. A full second-story addition usually demands a builder's risk policy and a conversation with your own insurer.
What Contractors Should Already Have, and How to Verify It
Reputable contractors carry general liability and workers compensation insurance. That is the baseline. But carrying a policy and having adequate coverage are two different things. A contractor with a $50,000 liability limit may look insured on paper, yet that amount disappears quickly if a fire causes $200,000 in damage.
Before you sign anything, request a certificate of insurance (COI) directly from the contractor's insurer, not from the contractor. The COI should list the policy limits, the effective dates, and the named insured. Call the insurer to confirm the policy is active. This five-minute phone call has saved homeowners from catastrophic losses.
You should also confirm whether the contractor's policy includes completed operations coverage. This protects you after the project ends if faulty workmanship causes damage months later. Some policies exclude this, leaving you to pursue the contractor personally, which is rarely fruitful if they have closed up shop.
When you connect with vetted professionals through a platform like USremodel, part of the screening process typically includes verifying that contractors hold active licenses and insurance. That pre-screening reduces your risk, but it does not eliminate your responsibility to review the paperwork yourself.
When You Need a Dedicated Renovation Policy
There is a threshold where your standard policy simply cannot stretch far enough. If your renovation involves structural changes, a significant increase in home value, or a project duration beyond a few weeks, your insurer may require a dedicated policy or a formal endorsement.
Builder's risk insurance is the most common dedicated product. It covers the project from the first day of demolition to the final inspection. Unlike a standard homeowners policy, builder's risk is designed for properties under construction. It typically covers:
- The existing structure and the new construction as it progresses.
- Materials and supplies stored on site or in transit.
- Temporary structures like scaffolding and fencing.
- Debris removal after a covered loss.
The cost of builder's risk insurance usually ranges from 0.5% to 2% of the project's total value, depending on the scope and location. On a $150,000 kitchen and living room remodel, that translates to roughly $750 to $3,000. Compared to the cost of rebuilding out of pocket, it is a reasonable investment.
You should also notify your existing insurer about the renovation. Some policies require you to disclose material changes to the property. Failing to do so can give the insurer grounds to deny a claim later. A simple phone call and a written confirmation can prevent that outcome.
Common Gaps That Catch Homeowners Off Guard
Even homeowners who think they are covered often discover gaps at the worst possible time. These gaps are rarely obvious, and they are rarely explained upfront by contractors or insurers. Knowing them in advance is your best defense.
One frequent gap involves materials stored on site. Your homeowners policy may cover personal property inside the home, but materials intended for construction often fall into a gray area. If a pallet of hardwood flooring is stolen from your driveway overnight, will your policy pay? The answer depends on whether the materials are classified as personal property or building materials, and that classification varies by policy.
Another gap involves water damage during construction. If a pipe is accidentally cut during demolition and water floods the subfloor, your standard policy may cover the resulting damage. But if the damage is traced to faulty workmanship, the insurer may deny the claim and point you toward the contractor's liability policy. That policy may have limits too low to cover the loss, leaving you to absorb the difference.
A third gap involves temporary living expenses. If your home becomes uninhabitable during the renovation, your policy's loss of use coverage may help. But many policies exclude losses caused by construction activities. If the renovation itself forces you out, you may be on your own for hotel bills and meals.
Finally, consider the effect of increased home value. If you add $100,000 in improvements but never update your dwelling coverage limit, you are underinsured. A total loss would leave you with a payout that does not reflect the home you actually built.
Steps to Protect Yourself Before Work Begins
The time to sort out insurance is before the first hammer swings. Once work is underway, your options shrink and your leverage disappears. A structured approach keeps you in control.
Start by reviewing your own policy with your agent. Ask specifically how the policy treats renovations, whether you need to add coverage, and what notice requirements apply. Get the answers in writing. Then collect and verify insurance documents from every contractor and subcontractor who will set foot on your property. Do not accept photocopies from the contractor. Request certificates directly from the insurers.
If your project is large, purchase a builder's risk policy or ask your contractor to provide one with you named as an additional insured. This ensures you have a direct claim path if something goes wrong. Keep a dedicated folder with all policies, certificates, and correspondence. If a claim arises, that folder becomes your evidence trail.
Finally, document the condition of your home before work begins. Take dated photos and video of every room, the exterior, and any valuables. This baseline protects you if a dispute arises about pre-existing damage versus damage caused during the renovation.
How Insurance Intersects With Your Contractor Agreement
Your contractor agreement should clearly state who carries which insurance and what happens if a loss occurs. Vague language like "contractor will maintain appropriate insurance" is not enough. The agreement should specify policy types, minimum limits, and the requirement that you be named as an additional insured on liability policies.
It should also address what happens if the contractor's insurance lapses mid-project. A reputable contractor will maintain coverage throughout, but you should have the right to request updated certificates at any time. If coverage lapses and you are not protected, you need to know immediately so you can take action.
Payment schedules should also reflect insurance milestones. For example, you might withhold final payment until you receive a certificate of completed operations coverage. This gives you leverage to ensure the contractor finishes the paperwork as thoroughly as they finish the work.
If you are working with a lead generation platform that connects you to contractors, ask whether the platform verifies insurance as part of its screening. Many do, but the scope of verification varies. Understanding what has been checked helps you decide what you still need to confirm on your own.
Filing a Claim During or After a Renovation
If a loss occurs, the claims process can be more complex than a standard homeowners claim. Multiple policies may be involved, and insurers may dispute which policy responds first. Your job is to document everything and communicate clearly.
Report the loss to your insurer immediately, even if you are unsure whether it is covered. Delays can give the insurer grounds to deny the claim. Provide photos, receipts, contracts, and any relevant correspondence. If the contractor's insurance is also involved, notify them as well and keep a record of every conversation.
Be prepared for an adjuster to inspect the damage. Walk them through the project scope and the timeline. If the adjuster's assessment seems low, get a second opinion from an independent adjuster or contractor. Insurance claims are negotiable, and a well-documented claim often yields a better outcome.
If the claim is denied, ask for the denial in writing with the specific policy language cited. You may be able to appeal, especially if the denial is based on a misinterpretation of the policy or the facts. In some cases, a letter from your contractor clarifying the cause of the loss can reverse the decision.
Home renovation insurance coverage for projects is not glamorous, and it is not the part of remodeling that gets pinned to Pinterest boards. But it is the foundation that keeps your investment safe when the unexpected happens. Review your policy, verify your contractor's coverage, and fill the gaps before they become expensive lessons. A few hours of paperwork now can save you from a financial disaster later.