
Home Renovation Contingency Fund: How Much to Set Aside
Set the right home renovation contingency fund how much to set aside with clear percentages by project type. Call (833)-365-8755 for contractor quotes.
By Julian Hayes
Learn more about Home Remodeling for guides, costs, and what to expect.
Compare Home Remodeling Pros Near You

Enter your ZIP code to compare top-rated local professionals and request free quotes.
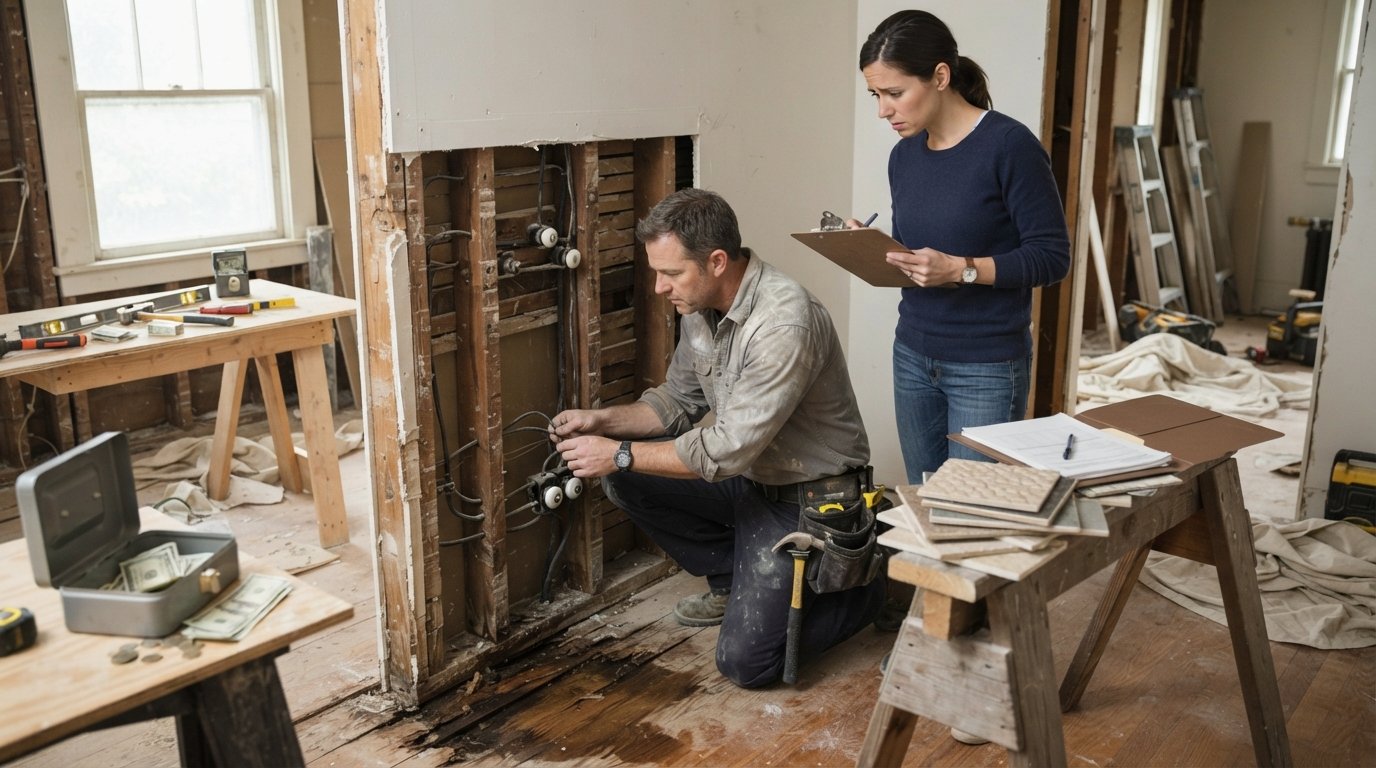
You have picked the tile, signed the contractor's estimate, and set a start date. Then the wall opens up and reveals old knob-and-tube wiring, or the subfloor is soft from a slow leak that nobody knew about. These surprises are not rare. They are the normal rhythm of remodeling an existing home. The single best protection against a stalled project is a properly sized home renovation contingency fund, and the most common question homeowners ask is simple: how much should I set aside? This guide gives you defensible numbers by project type and home age, explains how contingency differs from allowances and change orders, and shows you how to hold and release the money so it does its job.
What a Contingency Fund Is and Why It Is Not Optional
A contingency fund is money reserved for unknown conditions and unforeseen costs that fall within the agreed scope of work. It is not a slush fund for upgrades, and it is not the same as the allowances already written into your contract for items like tile or light fixtures. Contingency exists because renovation estimates are educated projections, not guarantees. Contractors price what they can see, and in older homes, much of the risk is hidden behind drywall, under flooring, and inside walls.
The financial logic is straightforward. A modest reserve of 10 to 20 percent of the project budget prevents a single surprise from turning into a financing crisis, a half-finished room, or a rushed decision made under pressure. Homeowners who skip contingency often end up paying for overages with high-interest credit or by cutting corners elsewhere in the build. Setting the money aside at the start, before demolition begins, is far easier than finding it mid-project when emotions and timelines are already stretched.
It also changes your negotiating position. When you know you have a reserve, you can evaluate a change order calmly, ask for documentation, and take a day to compare options. Without a reserve, every surprise feels like an emergency, and emergency decisions in construction are usually the most expensive ones.
How Much to Set Aside: Percentages by Project Type
The right percentage depends on how much unknown territory the project touches. Cosmetic work in a newer home carries less risk than structural work in a century-old house. Use the ranges below as a starting framework, then adjust upward for age, prior DIY work, and any known red flags from your inspection or contractor walkthrough.
- Cosmetic updates (paint, flooring, fixtures) in a home under 20 years old: 10 to 15 percent of the project cost. Risk is low because you are not opening walls or moving systems.
- Kitchen and bathroom remodels: 15 to 20 percent. These rooms concentrate plumbing, electrical, and ventilation in tight spaces, and older layouts often hide code issues.
- Full-home renovation or additions: 20 percent or more. Structural changes, permitting, and the sheer number of trades multiply the opportunities for surprises.
- Homes over 40 years old or with unknown renovation history: add 5 to 10 percentage points to the base range. Aging systems and past DIY work are the most common sources of overruns.
These percentages apply to the total contract price, not just materials. If your kitchen remodel is budgeted at 60,000 dollars, a 15 to 20 percent contingency means setting aside 9,000 to 12,000 dollars. That figure can feel large, but compare it to the cost of discovering rotted framing or a failed drain line with no reserve. The contingency is not wasted money. Whatever you do not spend stays with you at the end of the project.
Home age deserves special attention. In a house built before 1980, assume that any wall you open may reveal outdated wiring, galvanized plumbing, or insulation that no longer meets code. Each of those discoveries can add thousands of dollars and several days to the schedule. If you are still mapping out the sequence of work, our guide on how long home renovation takes explains how hidden conditions can extend timelines, which is another reason to keep contingency funds liquid and ready.
Contingency vs. Allowances vs. Change Orders
Homeowners often conflate three different buckets of money, and that confusion leads to underfunding. A contingency fund is your reserve for unknowns. An allowance is a line item in the contract that estimates the cost of a selection you have not made yet, such as a vanity, faucet, or tile. A change order is a formal, signed amendment that adjusts the contract price and schedule after work begins. Each plays a distinct role, and mixing them up can make your budget look healthier than it really is.
Allowances are not contingency. If your contract includes a 3,000 dollar allowance for bathroom tile and you choose tile that costs 4,500 dollars, that overage is a design decision, not an unforeseen condition. It should come from your discretionary budget, not from the contingency reserve. Similarly, a change order for added recessed lighting is a scope change you requested. Contingency is reserved for things nobody chose, like a hidden water leak or a beam that fails inspection.
Keeping these categories separate protects the reserve. Before the project starts, list your allowances and decide how you will handle overages on selections. Then treat the contingency as untouchable except for documented, unforeseen conditions. Contractors who understand this distinction will present change orders with photos and explanations, which makes it easier to release funds responsibly.
How to Hold Contingency Funds Separately
Where the money sits matters as much as how much you set aside. The reserve should be liquid, separate from your daily accounts, and clearly labeled so it does not get absorbed into everyday spending. A high-yield savings account dedicated to the project is the simplest solution. It earns a little interest, stays accessible within a day or two, and creates a clean paper trail.
Avoid locking contingency into long-term investments or tying it up in home equity you have not drawn yet. Renovation surprises require fast decisions, and you do not want to be selling assets or waiting on a lender when a contractor needs an answer to keep the schedule moving. If you are financing part of the project, keep the contingency in cash or a liquid account even if the main funding comes from a loan.
Set a clear release rule before demolition day. A workable rule is that contingency can be released only for conditions that could not have been reasonably discovered before work began, documented with photos and a written change order. Cosmetic upgrades, design changes, and items already covered by allowances are excluded. When you need to compare contractor bids or verify pricing before committing your reserve, resources like ContractorHomeQuotes can help you benchmark costs so you know whether a change order is fair.
When to Release Contingency Funds
Releasing contingency should be a deliberate step, not a reflex. The moment a contractor says, we found something, your first response should be to ask for documentation and a written change order. Review the photos, ask what happens if the condition is left as is, and confirm the cost against your original scope. Only then should you move money from the reserve.
A simple release checklist keeps the process disciplined. Confirm the condition is truly unforeseen, verify the change order matches the work described, and check that the price is reasonable for your market. If the amount is significant, get a second opinion or a quick comparison quote. Once approved, transfer only the amount needed for that specific item, not the whole reserve. This preserves the fund for later stages of the project, when new surprises can still appear.
At the end of the project, any unspent contingency returns to you. Many homeowners use it to replenish savings, pay down financing, or fund a small punch-list reserve for the first year of ownership. Treating leftover contingency as a refund rather than a reason to upgrade the finishes is one of the simplest ways to keep a renovation financially healthy.
Real Scenarios Where Contingency Saved the Project
Consider a bathroom remodel in a 1960s ranch home. The contractor removed the tub surround and found water damage extending into the framing and subfloor. The repair added 4,200 dollars and three days to the schedule. The homeowner had set aside 18 percent contingency on a 30,000 dollar project, roughly 5,400 dollars. The repair was covered without touching savings or credit, and the project finished on schedule with the original tile and fixtures.
In another case, a kitchen renovation in a home with previous DIY electrical work failed inspection. Bringing the wiring up to code required a licensed electrician and added 6,000 dollars to a 55,000 dollar budget. The homeowner had reserved 20 percent, or 11,000 dollars. The reserve absorbed the cost, and the remaining funds covered a small plumbing surprise behind the sink wall. Without that reserve, the project would have stalled for weeks while the family scrambled for financing.
These stories are common, not exceptional. The pattern is consistent: projects with a properly sized and disciplined contingency finish closer to plan, while projects without one tend to accumulate delays and debt. The reserve is not pessimism. It is project management.
Talking to Your Contractor About Contingency Without Encouraging Scope Creep
Some homeowners worry that mentioning a contingency fund invites upsells. The concern is understandable, but the solution is transparency with boundaries. Tell your contractor that you have a reserve for unforeseen conditions and that you expect change orders to be documented with photos, a written scope, and a fixed price. Make clear that design upgrades and optional additions will be evaluated separately and are not automatically approved.
Ask your contractor during the bidding phase what hidden conditions they typically encounter in homes of your age and type. A good contractor will appreciate the question and may adjust their initial walkthrough or recommend limited exploratory work before the contract is signed. That conversation also helps you calibrate your percentage: if the contractor flags multiple risk areas, lean toward the higher end of the range.
Finally, put the contingency rules in writing as part of your project agreement. Specify how change orders are submitted, how quickly you will review them, and what documentation is required. This protects both sides and keeps the reserve focused on genuine surprises rather than gradual scope expansion. When you are ready to compare vetted professionals for your project, 180 Remodel can connect you with contractors who work within clear budgets and documented change orders.
A well-sized contingency fund is the quiet difference between a renovation that finishes on your terms and one that drains your savings. Start with 10 to 20 percent depending on project type and home age, hold it separately, and release it only for documented unknowns. That discipline keeps your project moving and your budget intact.